 fahmi-reza
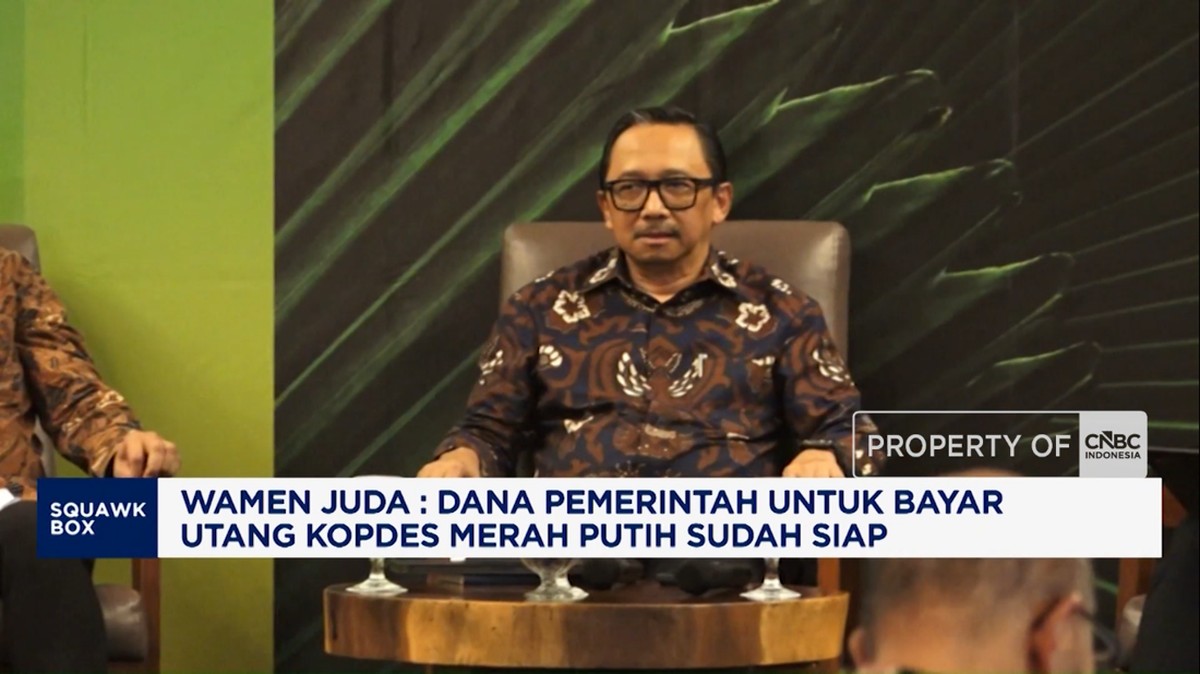
Ada satu hal yang jarang terdengar Associations dalam discussionsrocokolRedesain programARGS:programqtyawaLUWANGSIH. Behind theJnichsoftware behind the cheerful acronym, there is a pile of bills. Stringently, the government has now stated that the money needed to settleKopdes Merah Putih — cooperative villages or village cooperatives — liabilities that mature in September 2026 is already in place. For ordinary citizens who have never followed the cooperative saga from the beginning, this sounds like dry treasury jargon. Yet it is not. It touches directly on one simple question: when a cooperative that was formed to help small farmers and small businesses grow, eventually has to borrow, who ends up paying the bill?
The answer matters because cooperatives operate very differently from companies. They do not have shareholders chasing dividends, and they do not have a central management that can be fired by a board. If money runs short, the loss typically slides back to the people who joined — the farmers, the home processors, the neighborhood retailers who staked their own capital and sometimes their own savings into the cooperative. A missed payment therefore does not stay as a spreadsheet error; it becomes a trust problem.
That is why the government's claim about readiness of funds should not be dismissed as a routine budget statement. It is, in effect, an early warning that the Red and White cooperative model needs to be treated as a financial institution, not merely as a social program with a nice logo and a launch ceremony.
Why a September Deadline Becomes a Test
Kopdes Merah Putih refers to the cooperative villages program, an initiative in which farmer groups, fishers, and small traders pool resources, collectively purchase inputs such as fertilizer, feed, or tools, and sell harvests together so that the margin stays in the village rather than being lost to middlemen. The logic is sound in theory — buying in bulk lowers unit costs, and collective selling raises bargaining power. But collective schemes also inherit all the classic vulnerabilities of cooperatives: weak bookkeeping, unclear governance, decisions made by consensus that drag on for months, and capital structures that are far too thin to absorb a shock.
Bridging that gap requires credit. Loans taken out by cooperatives, whether from banks or from state channels, come with a repayment date. Once that date arrives, the obligation is no longer a plan or a target; it is cash that must move. September 2026 is significant because it is the first major test date where obligations are scheduled to fall due in bulk. Missing it would expose the program to penalties, reputational damage, and — most damaging of all — the withdrawal of members who had signed up precisely because they were promised the collective would protect them.
Where the Money Comes From
The government's assurance points to budgetary preparations rather than improvisation. In practice, funding for obligations of this kind usually comes from three places: direct state budget allocations approved in the state revenue and expenditure framework, funds set aside through development financing or bonds, and repayments flowing back from cooperatives that have begun operating commercially and generating turnover from the sale of harvests and goods.
The third source is the one worth watching most closely. If a cooperative can repay its own obligations, the program is fundamentally sound, and any state support is simply a bridge. If the government must keep subsidising repayments because operating income remains weak, then the model has not yet reached the point ofself-sustaining operations, and the word “cooperative” is doing heavy lifting it may not deserve. Transparent reporting on the proportion of funds actually recovered from cooperative cash flow would give the public a much clearer picture than a single reassurance about readiness.
What Analysts Say Must Be Watched Next
Financial readiness and institutional readiness are two different things, and the second is harder to build. Money can be allocated in a budget cycle; accounting standards, audit trails, and enforceable governance take years to mature.
A cooperative that cannot produce audited financial statements on time will eventually struggle to repay on time. The payment date is merely the symptom; the real problem is always the quality of the books.
Several points deserve attention in the months ahead. First, whether repayment capacity is being measured per cooperative unit, rather than aggregated into a national average that looks healthier than reality. Second, whether boards of directors and supervisory boards are being empowered — or merely blamed — when a unit fails. Third, whether the program builds a genuine exit path for cooperatives that genuinely cannot survive, so that members' savings are protected rather than quietly absorbed.
For now, the September 2026 maturity schedule is best understood as a checkpoint rather than a finish line. If funds are in place and arrive on time, the cooperative movement gains credibility it desperately needs. If they are delayed, the damage will extend far beyond the cooperatives directly affected: neighbouring communities will hesitate to join, lenders will raise their risk premiums, and a program designed to strengthen the small economy will instead be remembered as an expensive lesson.
The good news is that the government is signalling it understands the stakes. The better news would be a full, public disclosure of the repayment mechanics — who owes what, to whom, and at what interest cost. That kind of transparency is what turns a promise about funding into something citizens can actually verify.




Comments (0)